
2026 Korea Travel Insurance Guide: How to Choose, Essential Coverage & Real User Experiences
How much does it cost to see a doctor for a cold in Korea? It depends on the hospital and treatment, so it's hard to estimate before you go; if you unfortunately twist your ankle while shopping in Myeongdong and need the ER, it costs even more. Medical expenses in Korea are genuinely expensive.
This article helps you quickly understand: whether you really need travel insurance for Korea, which coverage is essential, how to pick a plan for short and long trips, and real insurance experiences from Dcard users. Premiums depend on trip length and coverage — go by each insurer's online quote.
TL;DR: Korea doesn't mandate travel insurance, but seeing a doctor abroad is expensive — insurance is strongly recommended; premiums depend on trip length and coverage, so go by the insurer's online quote. Essential coverage is overseas medical (recommend at least NT$500,000), followed by flight delay and personal property theft.
Korean ER Visits Are Extremely Expensive — Strongly Recommend Buying Travel Insurance
Bottom line upfront: strongly recommend buying it. Korea's entry rules don't require travel insurance, but given the medical costs, going uninsured is basically gambling.
Where Do Medical Costs Come In? Common Situations
Medical costs in Korea vary a lot by hospital tier and treatment. Common situations you might run into:
- General clinic visit (cold, gastroenteritis)
- ER registration + basic treatment
- Fracture ER + X-ray + immobilization
- Food poisoning hospitalization
- Appendicitis surgery + hospitalization
Actual costs go by the hospital's charges.
When seeing a doctor in Korea, also budget for the extra costs of finding a translator due to the language barrier and of getting there and back.
We reviewed insurance-related discussions on Dcard's Korea travel board over the past six months and found the most common claims involve: food poisoning (from Korean BBQ or street food), walking injuries (wearing unfamiliar shoes while walking all day), and winter falls (icy roads are genuinely slippery).
Is Credit Card Travel Insurance Enough?
Many people think: I get travel insurance with my credit card when I buy the ticket — that should be enough, right?
Honestly, most credit card travel insurance has these limitations:
- Coverage tends to be low, with medical coverage potentially only NT$200,000-500,000
- Strict activation conditions: must use the card to purchase full-fare tickets or 80%+ of tour package costs
- Some coverage items may be excluded (e.g., flight delays, baggage loss)
- Claims process is more complicated
We recommend treating credit card insurance as a "bonus" rather than your only coverage. Taking out a comprehensive travel insurance policy of your own provides much greater peace of mind.
How to Choose Korea Travel Insurance?
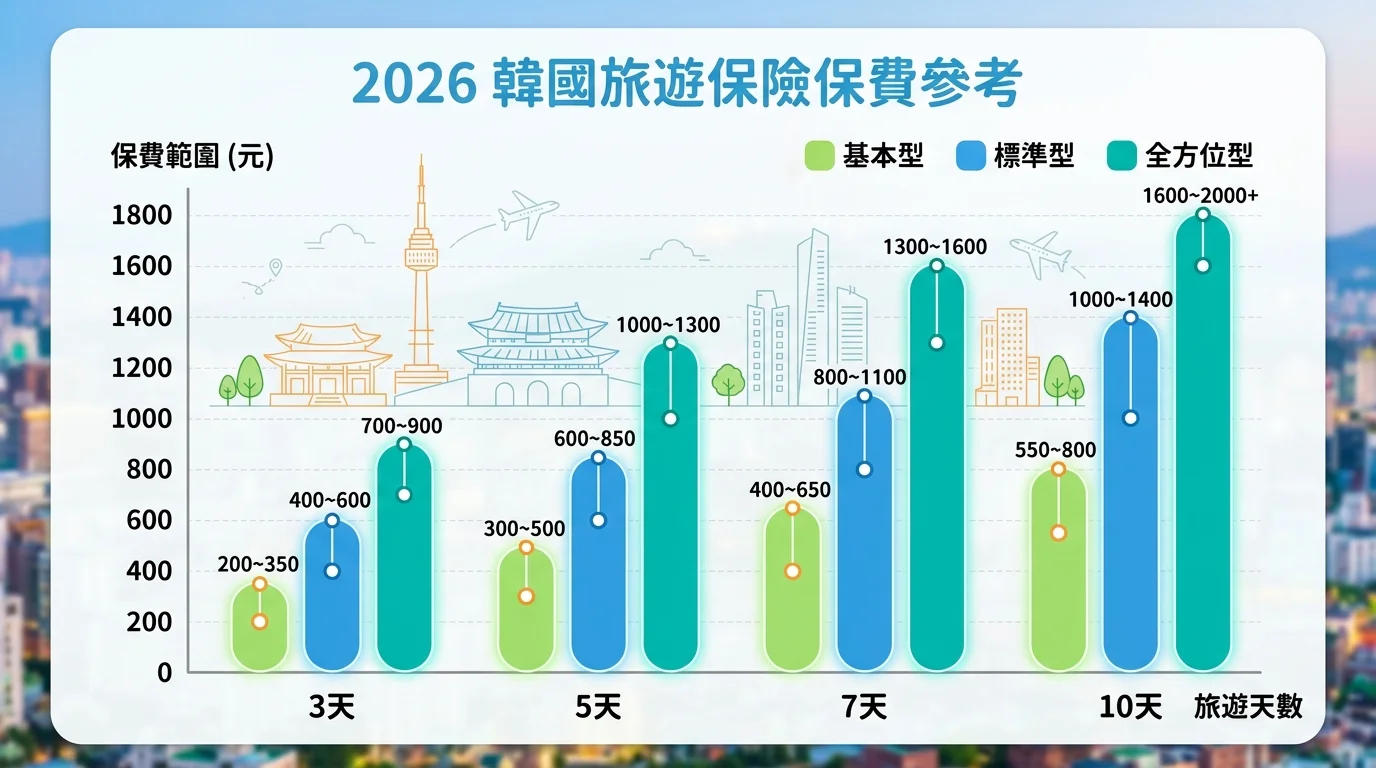
Premiums depend on trip length, age and coverage — go by each insurer's online quote. The two most common Korea trip types are quick getaways and deep dives, with different recommended plans for each.
Short Trip (3-5 Days) Recommended Plans
Quick Korea trips are short, so premiums are relatively low — go by the online quote for the actual amount.
Key selection criteria:
- Medical coverage at least NT$500,000
- Includes flight delay coverage (Korean winter flights have frequent delays)
Long Trip (7+ Days) Recommended Plans
For 7+ day deep dives, longer trips mean higher risk, so we recommend:
- Increase medical coverage to NT$1,000,000
- Add personal property theft coverage
- Choose flight delay plans that pay out after 4 hours
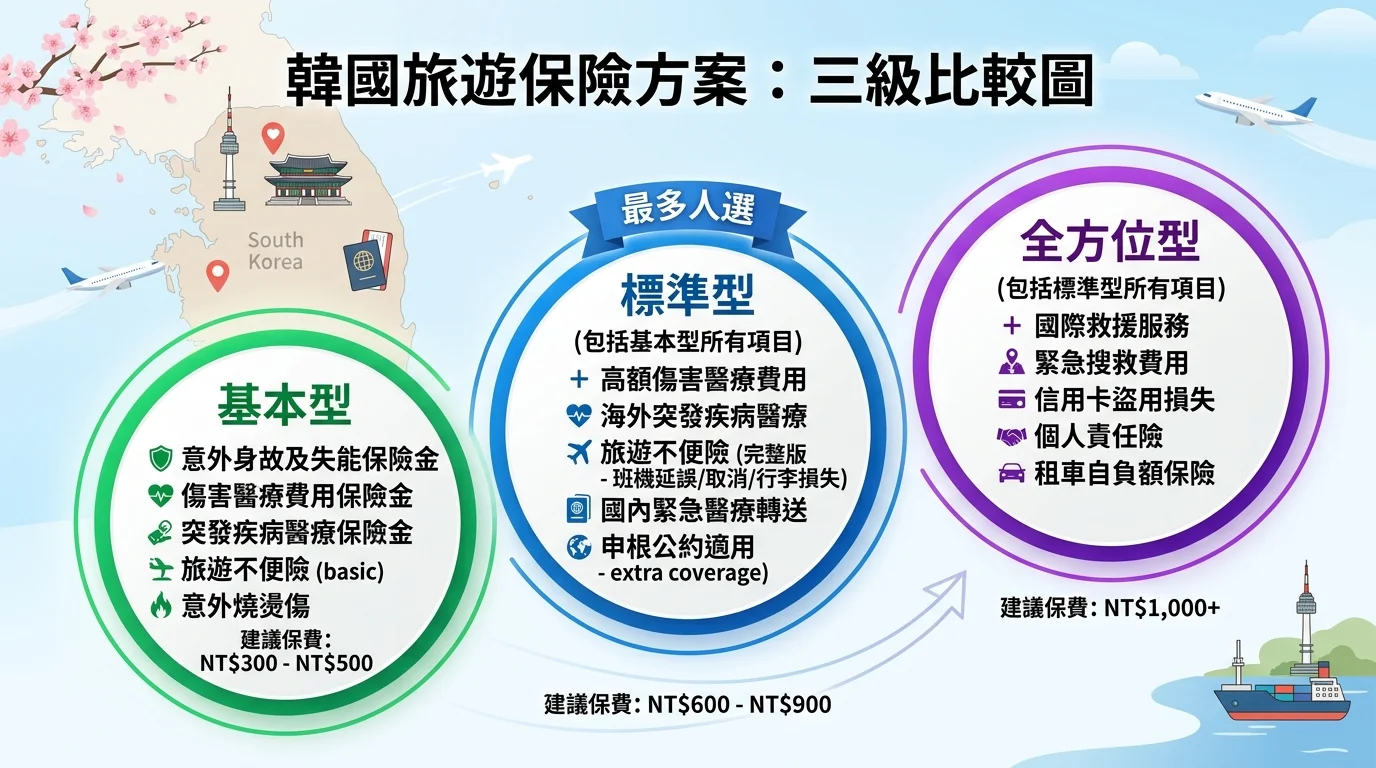
Plan Type Comparison Table
| Plan Type | Medical Coverage | Flight Delay |
|---|---|---|
| Basic | NT$500,000 | Some include |
| Standard | NT$1,000,000 | Included |
| Comprehensive | NT$2,000,000 | Included (with hotel compensation) |
Actual premiums vary by age and coverage details — go by each insurer's online quote.
The Standard plan has higher medical coverage and includes flight delay cover, which suits most trips; the Comprehensive plan suits those with high trip expenses or families traveling with children who want extra peace of mind.
For an overview of insurance plans for all destinations, see Travel Insurance Complete Guide
What Coverage Is Essential for Korea Travel Insurance?
Cheap premiums don't mean everything is covered. For Korea travel, make sure these items are included.
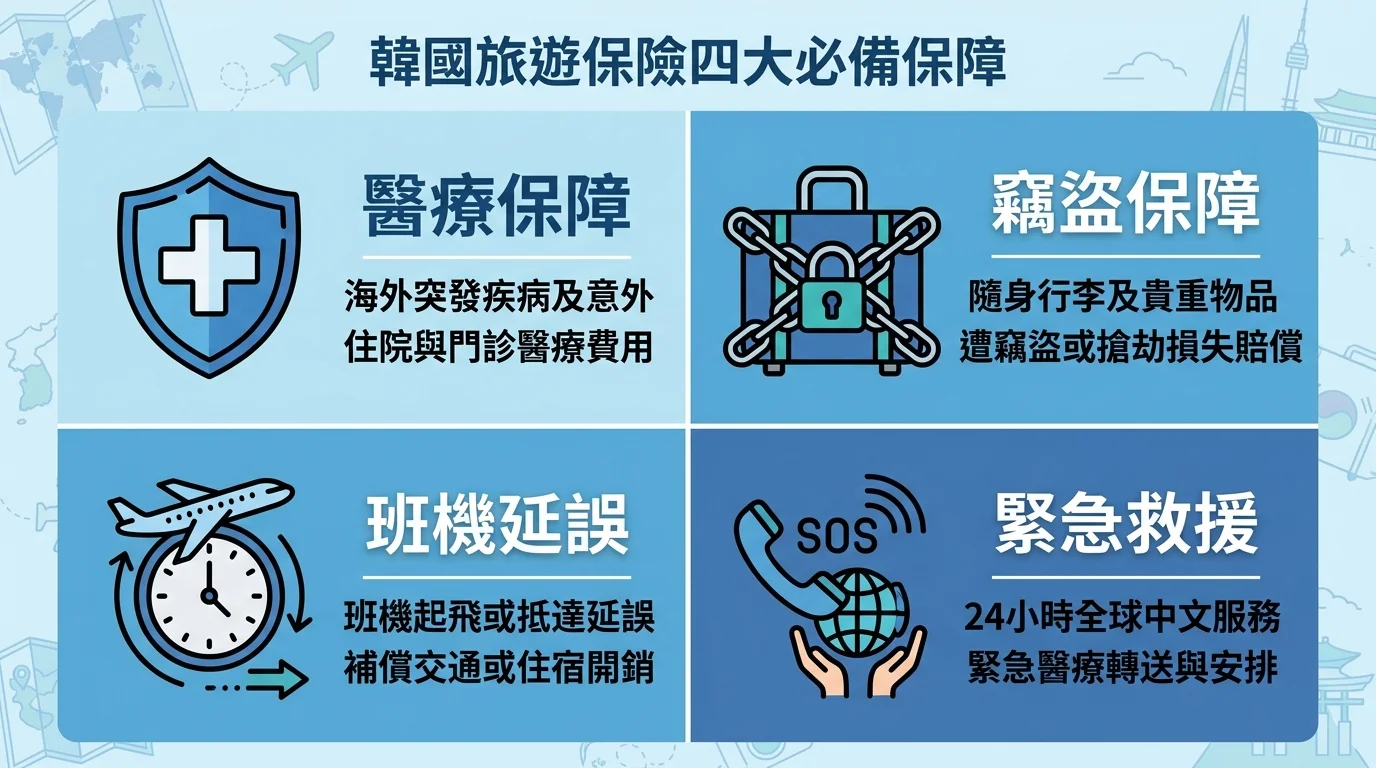
Overseas Emergency Medical Care
This is the single most important coverage — bar none. Getting food poisoning, catching a cold, or getting injured from a fall in Korea is not uncommon, especially for first-time visitors adjusting to the different environment.
Recommended coverage amounts:
- Visiting Seoul, Busan, and other major cities: at least NT$500,000
- Trips over 7 days or traveling with children: recommend NT$1,000,000
Personal Liability & Theft Coverage
Pickpocket incidents in Korean tourist areas aren't rare, especially in crowded spots like Myeongdong, Hongdae, and Dongdaemun. Phone theft and wallet snatching do happen occasionally.
Personal property theft coverage compensates for stolen losses — while not covering the full amount, you can at least recover a portion. Additionally, if you accidentally damage something at a hotel, third-party liability insurance helps share the compensation burden.
Flight Delay & Baggage Loss
Flight delay rates on Korea routes aren't low. These periods are especially prone to delays:
- Winter (December-February): Blizzards causing flight delays or cancellations
- Typhoon season (July-September): Affecting southern Korea and entire flight routes
- Korean holidays: Airport crowds surge, ground crew processing slows down
Flight delay coverage compensates for extra accommodation and meal costs due to delays. Choose plans that pay out starting at 4 hours for the most practical coverage.
Additionally, choose plans with "emergency assistance service." Dealing with medical care in Korea with a language barrier is especially frustrating — having a Chinese service hotline to call for help makes the premium worthwhile from just one use.
For families bringing children to Korea, insurance considerations are even more important — don't forget to check Family Travel Insurance Guide
Korea Travel Insurance FAQ
Q: Is travel insurance mandatory for Korea?
A: Korea doesn't have mandatory requirements, but seeing a doctor abroad is expensive and there's a language barrier, so insurance is strongly recommended. For short-trip policies, go by the insurer's online quote for the actual premium.
Q: Is credit card travel insurance enough for Korea?
A: Most credit card travel insurance has low coverage (NT$200,000-500,000) and strict activation conditions (must use card for full-fare ticket purchase). We recommend treating it as a bonus rather than your sole coverage. Taking out a comprehensive policy of your own is much more reassuring.
Q: How much does Korea travel insurance cost?
A: Go by each insurer's online quote for premiums. Main factors affecting premiums are trip duration, coverage scope, and medical coverage amount.
Q: How to choose insurance for a short quick trip?
A: For 3-5 day Korea quick trips, the Standard plan is recommended. Ensure overseas medical coverage (at least NT$500,000) and flight delay coverage are included. No need for the Comprehensive plan — save the premium for an extra meal of Korean BBQ.
Plan a Taiwan Family Trip After Your Korea Return | No Insurance or Visa Needed for Domestic Travel
After returning from Korea, why not plan a family trip within Taiwan to let the kids burn energy and give parents a break too. Domestic travel means no worrying about insurance, visas, or language barriers — bringing the whole family out is super easy.
Cool Price Travel Domestic Hotel Vouchers | Valid for 6 Months, Book When You're Ready
Don't miss great deals for domestic travel either — Cool Price Travel vouchers are valid with flexible dates. Flexible, easy family outings that won't hurt your wallet.
Half-board plans | Best value stay-with-meals deals
Want more options?
Further Reading
- Travel Insurance Complete Guide
- Family Travel Insurance Guide
- Hotel Booking Apps & Money-Saving Tools
- Taiwan Travel Subsidy Guide
References
- Financial Supervisory Commission — Travel Insurance Regulations
- Bureau of Consular Affairs, Ministry of Foreign Affairs — Korea Travel Information
- Various insurance company official online quote tools, 2026